By Abebaw Zeleke, Mitiku Zeleke, ORDA Ethiopia and Nardos Masresha, GOPA MetaMeta
This blog is part of a dossier on locally-led adaptation, featuring insights and lessons from the Reversing the Flow (RtF) program. RtF empowers communities in Bangladesh, Burkina Faso, Ethiopia, Kenya, and Sudan to build climate resilience through direct funding and a community-driven, landscape approach.
On a small farm in Ethiopia’s Amhara Region, an ox does far more than pull a plough. It prepares fields before the rain arrives. It helps produce the harvest that feeds a family. It represents savings, security, and social status. At the right moment, it can also be sold, generating the capital to invest again.
In Koti Kebele, where recurring droughts, land degradation, and limited financial services have long constrained rural livelihoods, that single animal is becoming something even more important. It helps to tell a new story about locally led development.
Through the Reversing the Flow (RtF) Project, hundreds of households across six micro-watersheds Adafit, Chincho, Dawit-Degami, Dewel Washaye, Gomenge, and Kurfi have gained access to revolving livelihood loans managed not by banks or project staff, but by their own watershed committees. These loans are helping families invest in livestock, poultry, and other income-generating activities while building something even more valuable than household income: community-managed financial institutions.
The story begins with an ox. But it is really about trust.

More than a loan
For many rural families, borrowing money has traditionally meant either finding a willing relative or avoiding credit altogether. Formal financial services are often distant, difficult to access, or poorly suited to smallholder farmers.
The RtF revolving fund was designed differently.
Each watershed manages its own fund through locally developed bylaws. Community members decide who receives loans, how repayments are managed, and how the money will continue circulating within the community. Rather than ending with a single beneficiary, every repayment finances another household’s opportunity.
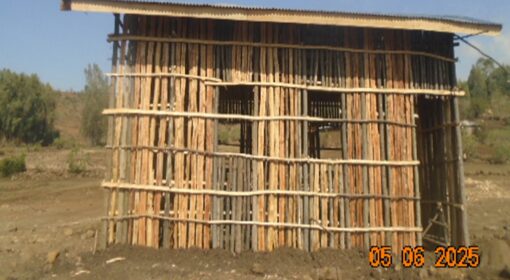
By the first quarter of 2026, the fund had already disbursed ETB 11.27 million (~€59,946.00) in revolving loans to 494 households, complemented by 11 Village Economic and Social Associations (VESAs) building financial literacy and resilience at village level. Watershed committees, meanwhile, have started constructing their own offices, a small but telling sign of institutions built to last, as they move toward becoming legally registered cooperatives.
Unlike a grant, the money is expected to be returned. Unlike a commercial loan, it remains rooted in the community.
The ox that earned twice
Many borrowers used their loans to purchase oxen. At first glance, this appears to be a straightforward livestock investment. It isn’t.
Families commonly used the newly purchased ox first to plough their own land sometimes pairing it with an existing ox to complete agricultural work that would otherwise require hiring labor or renting animals. Only after the farming season did they fatten the ox and sell it at a higher price.
One investment. Two economic returns.
The ox first increased agricultural production. Then it generated cash income. Few financial investments work twice before being sold. This one did.
Small investments, big ambitions
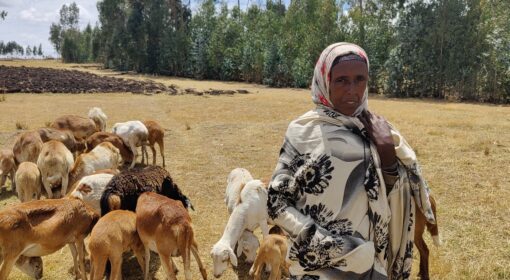
Not every household chose cattle. Some invested in goats or sheep. Others chose poultry. Across the watershed, community members shared stories that illustrate how even modest investments are beginning to change household economies.
One woman purchased livestock with a loan of approximately 20,000 Birr (~€106.00) and later sold the animal for around 55,000 Birr(~€293.00). Another borrower bought a young calf that was eventually sold for approximately 60,000 Birr(~€320.00).

Who decides?
Perhaps the most interesting feature of the revolving fund is not what people buy. It is who decides.
Loan recipients are not selected by project staff. Communities have developed their own criteria. Households that actively participate in restoring degraded land receive priority communal labor on area closures, watershed conservation, and other shared works forms part of the selection process. Where more eligible households exist than available funds, lotteries are sometimes used to ensure fairness.
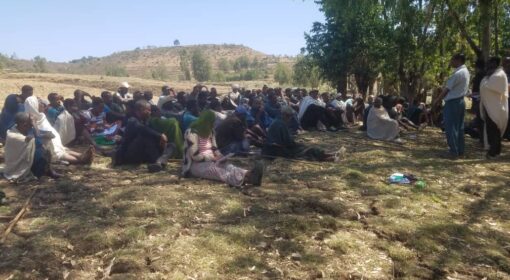
In one community meeting, residents even debated whether the available budget should provide larger loans to fewer households or smaller loans to many. Some argued that inflation had made the existing loan ceiling too small to create meaningful change. Others believed reaching more families mattered more. The community ultimately chose the second option. The decision was not imposed. It was negotiated.
As Fentanesh Aneliy, a committee member in the Kurfi watershed, put it: “The work we do is not imposed from outside it is carried out by us, the people, with strong belief in its value.”
That conviction reflects one of the central ideas behind locally led adaptation: communities making difficult choices together, weighing equity against impact according to their own priorities.
Trust that keeps growing
Every revolving fund depends on repayment. At first, not everyone believed that would happen.
According to ORDA’s project coordinator, some community members initially feared that once money was repaid, it might disappear back into the project rather than remain available for future borrowers. Those concerns gradually faded. As loan cycles continued, people watched repayments enter the community account and quickly become new loans for neighbors waiting their turn.
The “Abebech Gomenge” Saving Association, formed under the Dawit-Degami Watershed Committee, tells that story in miniature. It began in 2018 E.C. with 14 members; it has since grown to 28, split evenly between women and men. Each member saves 100 Birr a month into a collective fund, which has already issued loans totaling 16,000 Birr, enabling members to buy and fatten livestock and expand small businesses repaid in rotation, so the next member’s turn always comes.
Confidence grew alongside the fund itself. Money that once seemed temporary became something permanent. Not because the amount increased. Because trust did.
Building institutions, not dependence
The revolving fund is also changing the way communities organize themselves.

Each watershed now manages bank accounts in its own name through elected signatories, while moving toward formal cooperative registration. In Kurfi, the committee recently restructured itself from 24 members down to 16, built, in the chairperson’s words, “upon the full participation and trust of the community.” In Gomenge, all 22 committee members work toward the same goals, and the committee makes a point of ensuring that members with physical disabilities can contribute in ways suited to their abilities.
Loan records, repayments, and financial decisions increasingly belong to the watershed communities themselves, rather than to an external organization. Alongside the revolving fund, VESAs provide additional savings opportunities modest financial systems that, together, represent something much larger.
Communities are gradually learning not only how to borrow money, but how to govern it.
Livelihoods that support landscapes
One concern often raised in restoration Projects is that livestock production can place additional pressure on recovering landscapes. The communities of Koti Kebele are aware of this tension.
Many households are gradually moving toward cut-and-carry feeding systems, harvesting fodder rather than allowing unrestricted grazing. The transition is still incomplete, but the evidence of what protection alone can achieve is already visible.

In the Chincho watershed, where a once-barren, flood-damaged slope has been enclosed and treated, native plant species tenbelel, kitkita, muja, qamo have returned, and so has wildlife: partridges, guineafowl, and duikers are now seen in an area that had none.
That kind of recovery reflects a broader understanding emerging across the watershed: healthy landscapes and healthy livelihoods are not competing objectives. Each depends upon the other.
Real investment
Development Projects often measure revolving funds by the amount of money disbursed. How many households receive loans? How much was repaid? How many livestock were purchased?
Those numbers matter. But after spending time with watershed committees and community members, another measure seems equally important.
The revolving fund is investing in people’s confidence that they can manage shared resources together. Every repayment says something. Not simply, “I have settled my debt.” But rather: “I want someone else to have the same opportunity I had.”
That may be the greatest return of all. Because in Koti Kebele, the most valuable asset is no longer the ox. It is the community’s growing belief that development is something they can finance, govern, and sustain together.